Should You Buy Now or Wait Until 2027? Here’s What the Experts Are Forecasting
When it comes to real estate, almost everyone is asking two main questions:
What’s next for mortgage rates?
Where are home prices heading?
If you are weighing whether to move in the coming months or hold off until 2027, expert projections offer a clear perspective: expect a steady, balanced housing market.
Forget wild swings, sudden drops, or erratic price spikes. The market is settling into a calmer rhythm—and a predictable market makes planning your next move much simpler.
Here is what you need to know to make the right decision for your situation.
1. Mortgage Rates Are Expected to Hold in a Steady Range
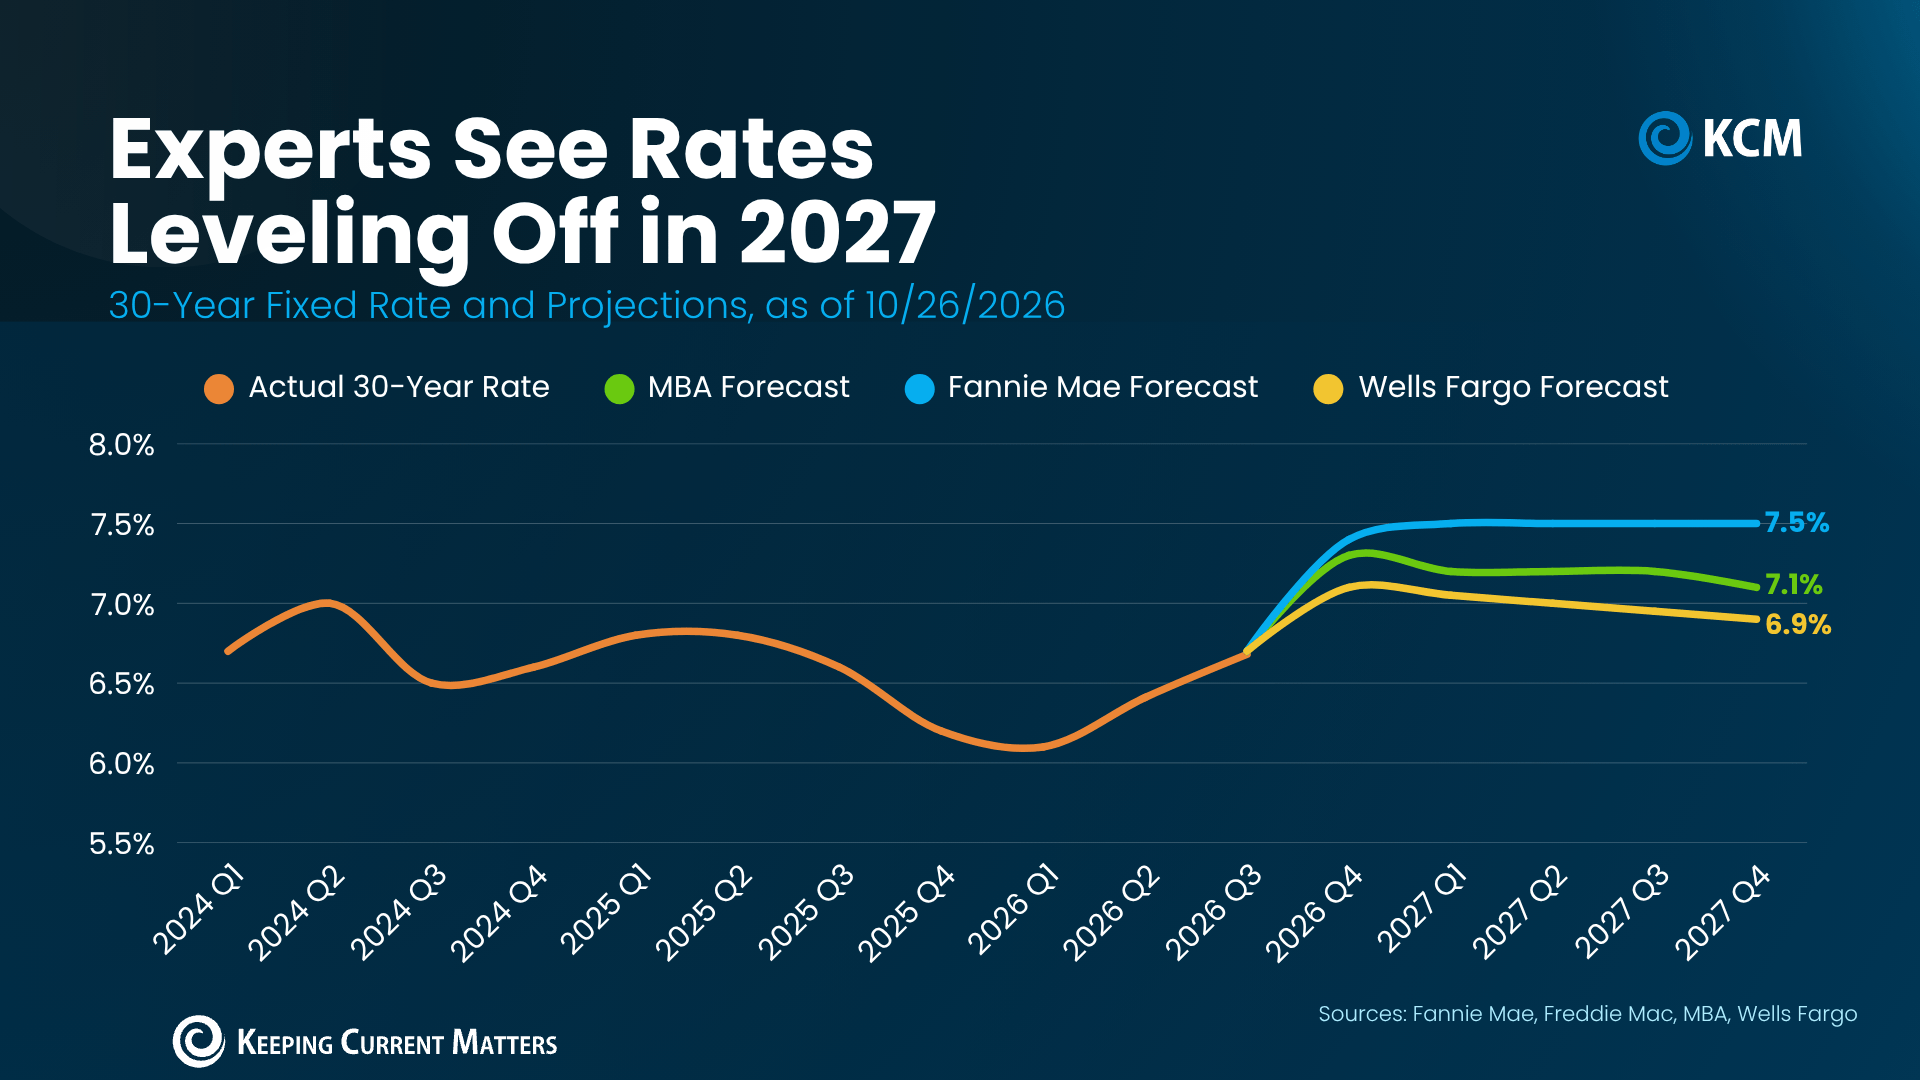
Many home buyers are holding out hope for a dramatic drop in rates. However, major industry forecasts—including recent outlooks from Fannie Mae, the Mortgage Bankers Association (MBA), and Wells Fargo—indicate that 30-year fixed rates will remain elevated and hover in a steady range through 2027.
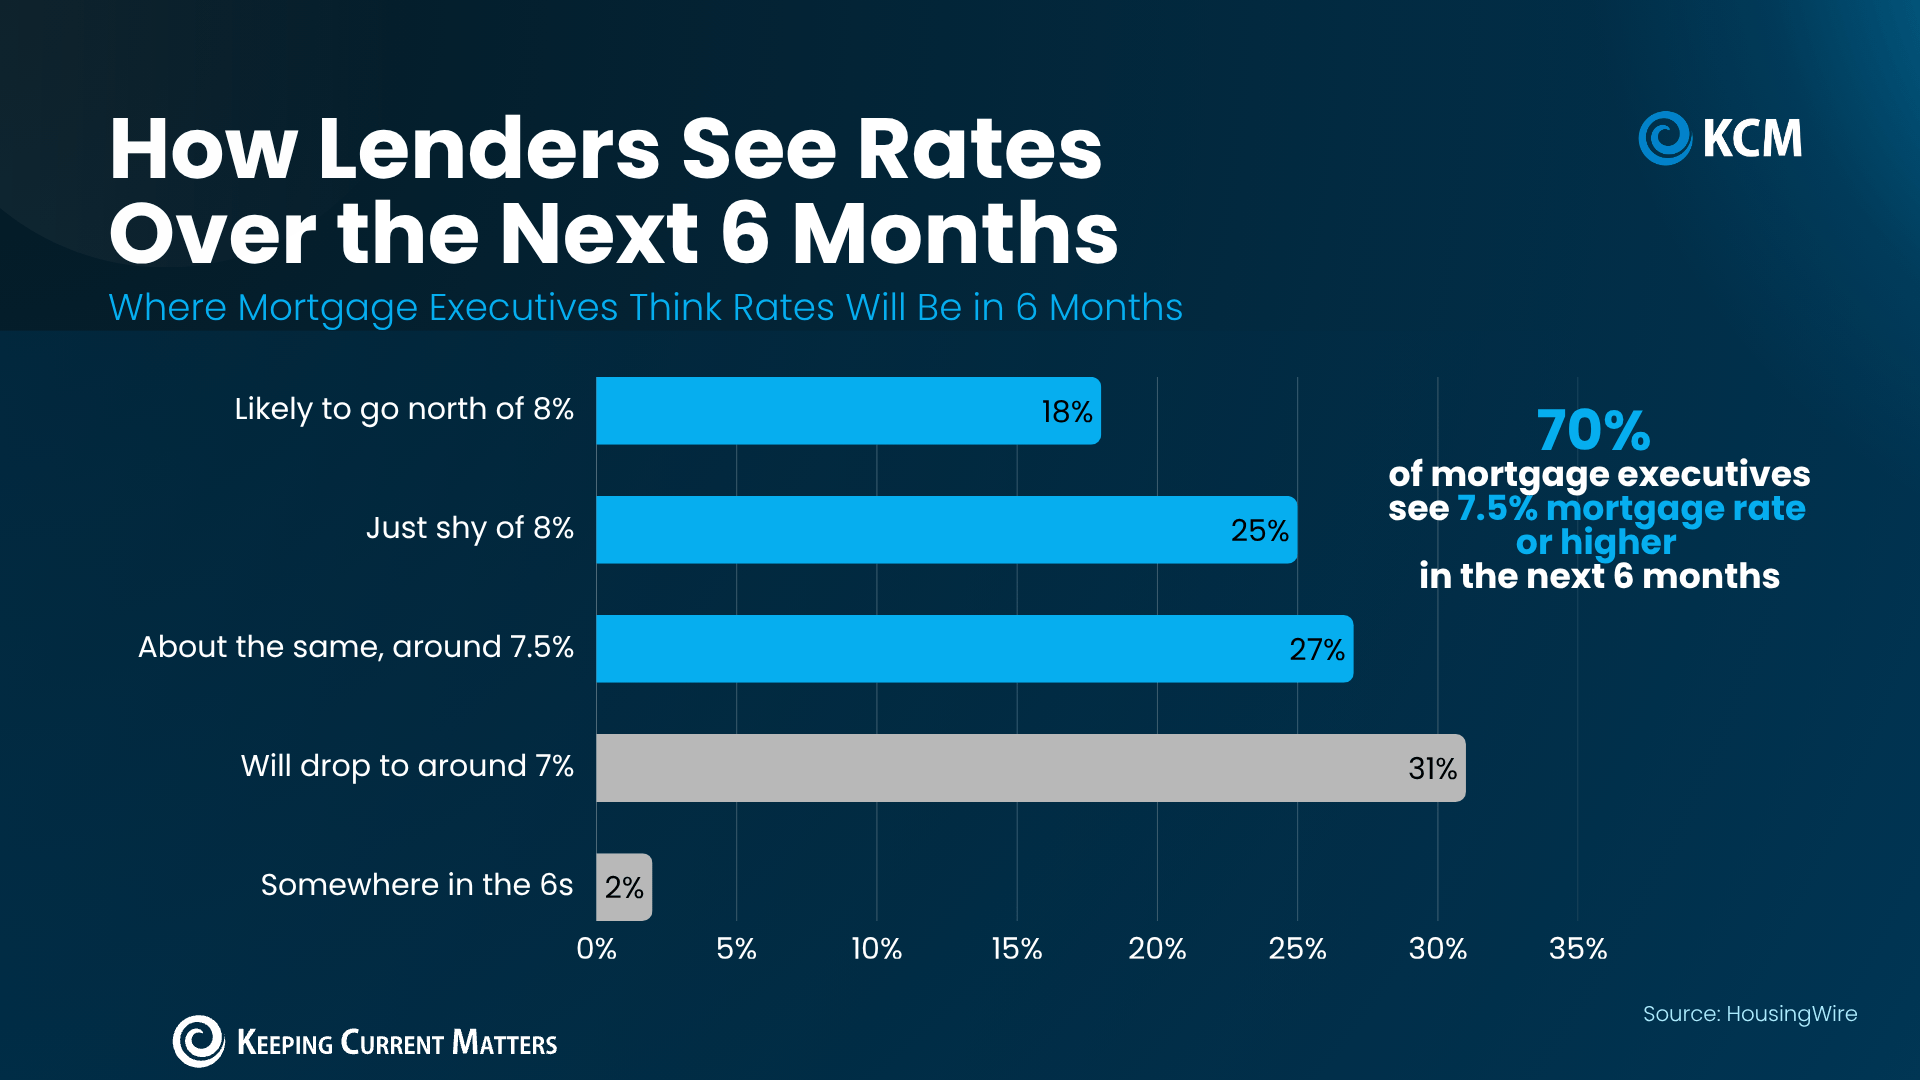
Lenders and industry executives share a similar view. In a survey conducted by HousingWire,70% of mortgage executives stated they expect rates to remain near 7.5% or higher over the next six months.
Why are rates staying in this range? As Chen Zhao, Head of Economics Research at Redfin, explains:
"Until the underlying economic fundamentals—everything from oil prices to AI—that are keeping rates high change, mortgage rates are unlikely to fall significantly."
What This Means for You
Rather than waiting on sidelines for a major drop that may not materialize, focus on what you can control. Even in a flat rate environment, you can take practical steps to secure a better deal:
Optimize Your Credit Score: Even a modest bump in your credit score can qualify you for a lower interest rate tier.
Explore Different Loan Programs: Various loan types (FHA, VA, conventional, or specialty programs) feature different rate structures and down payment options.
Consider Buying Down Your Rate: Paying discount points upfront allows you to permanently or temporarily lower your rate and lower your monthly payment.
2. Home Prices Will Keep Rising—Just More Slowly
If you are holding out for home prices to drop significantly, economic forecasts suggest otherwise.
Projections from Fannie Mae, MBA, and Wells Fargo show home prices appreciating nationwide at a modest rate of 1% to 1.5% annually through 2027.
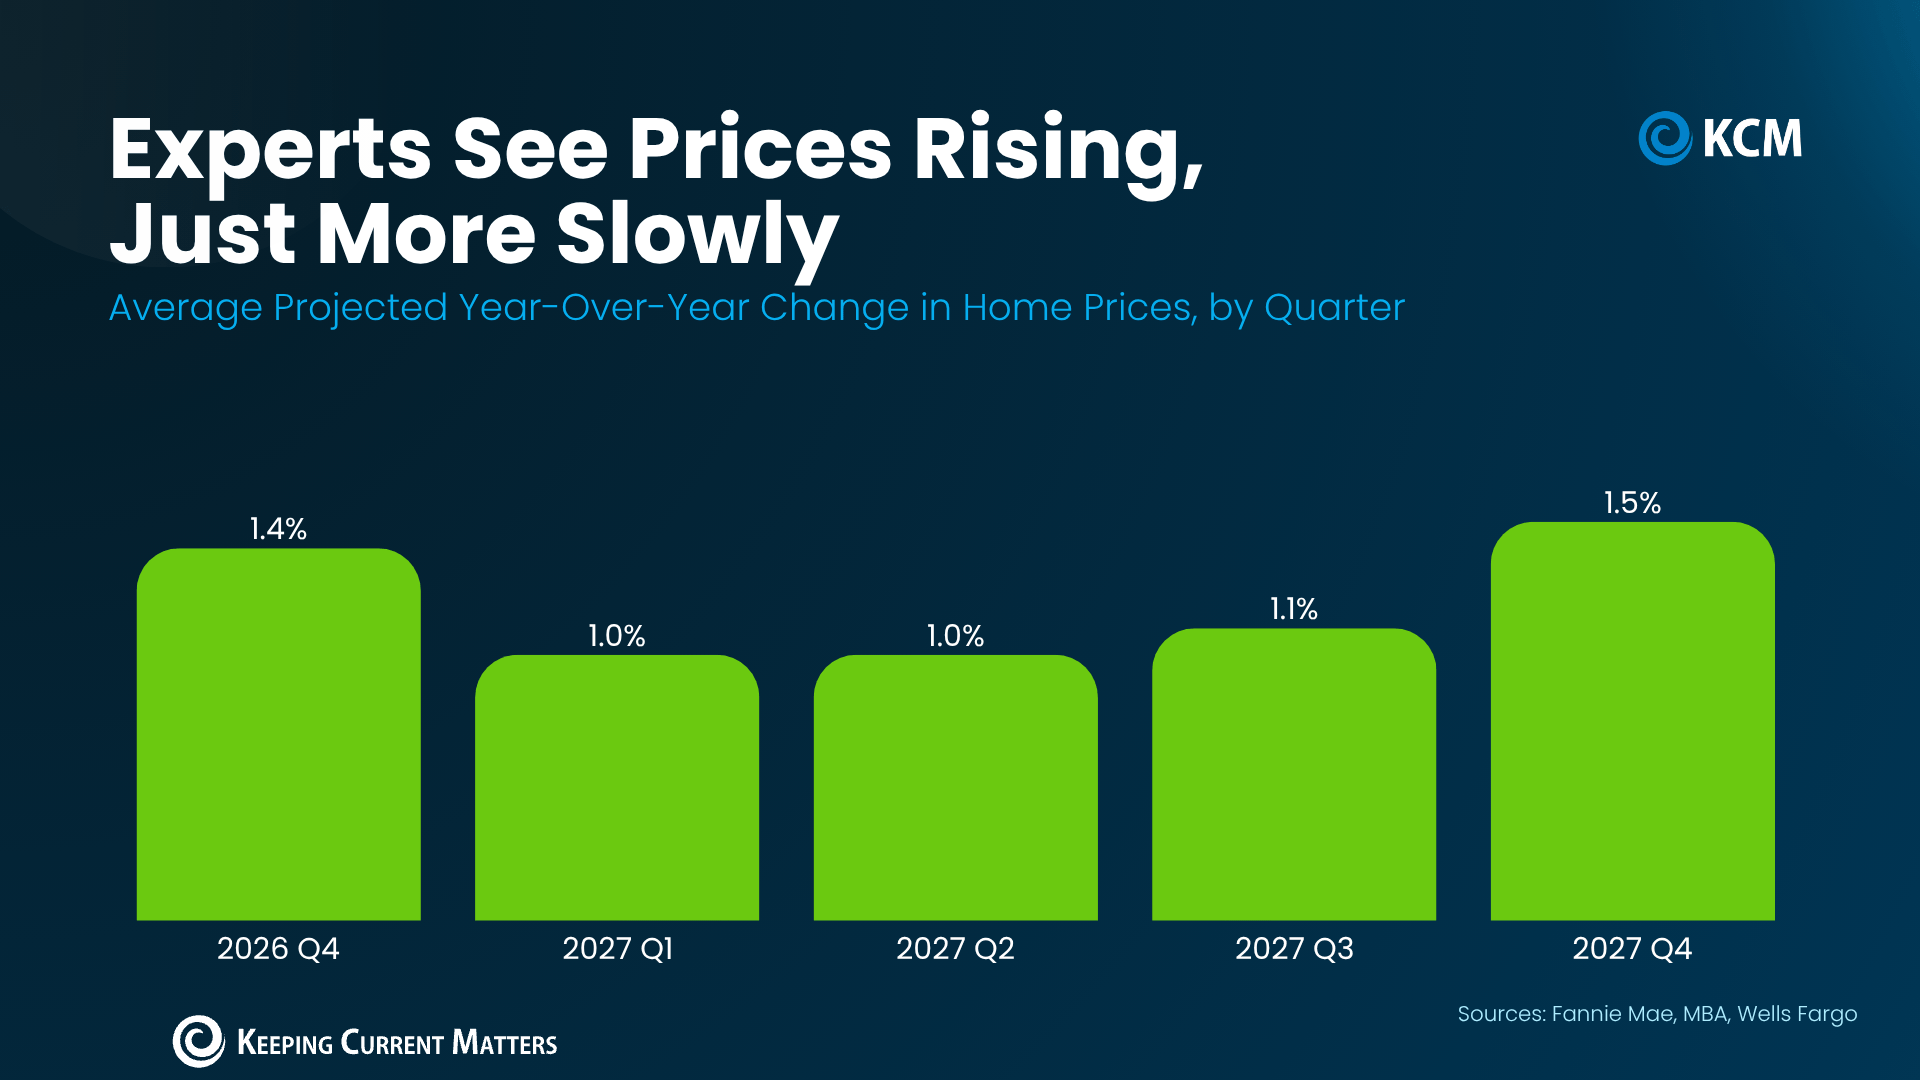
What This Means for Buyers and Sellers
For Sellers: Your home equity remains protected. Values are holding steady, so you can count on retaining your property's worth.
For Buyers: Slower price growth takes away the frenzy of bidding wars and gives you room to shop carefully. However, waiting won't make homes cheaper—delaying your purchase means paying slightly more later on.
Keep in mind that these are national averages. Real estate is local, so price movements in your specific city or neighborhood may differ.
3. The Best Time to Move Is When It Fits Your Life
In a volatile market, timing is everything. But in a steady market, the pressure to "time the market perfectly" disappears.
Whether you need a bigger layout for a growing family, want to downsize to minimize upkeep, or need to relocate, your personal milestones—not market speculation—should drive your decision.
The Bottom Line
If you’re debating whether to buy now or wait until 2027, remember: experts anticipate a stable housing market, with mortgage rates hovering near current levels and prices rising at a slow, manageable pace.
Instead of waiting for a big market shift that may not come, connect with a local real estate agent and a trusted mortgage lender. Run the numbers based on today's prices and rates so you can make a decision rooted in your personal financial goals rather than the headlines.
