High Mortgage Rates Actually Give Homebuyers a Hidden Advantage Right Now
If you’ve been keeping an eye on mortgage rates lately, it’s easy to feel stuck on the sidelines. With rates hovering above 7%, plenty of prospective buyers have hit pause, hoping to wait out the storm until borrowing gets cheaper.
Here is what gets overlooked when you only focus on the interest rate: in real estate, you almost always have to choose between low rates or negotiating power. Getting both at the same time is a unicorn. While today’s rates aren't ideal, the market is quietly handing buyers the strongest leverage they’ve had in years.
The Seesaw of Rates and Leverage
To see why you can’t usually have both, look back at the frenzy of 2020 and 2021. Mortgage rates dropped near 3%, and buyers flooded the market all at once. Cheap money sounded great on paper, but it created a brutal catch: far more buyers than available homes.
Sellers held every single card. Homes sparked bidding wars, buyers routinely paid tens of thousands over asking, and essential protections like home inspections were waived just to get a foot in the door. As Realtor.com Senior Economist Jake Krimmel notes:
“Seller’s markets peaked at 98 of 100 metros in spring 2022 after two years of mortgage rates near 3%.”
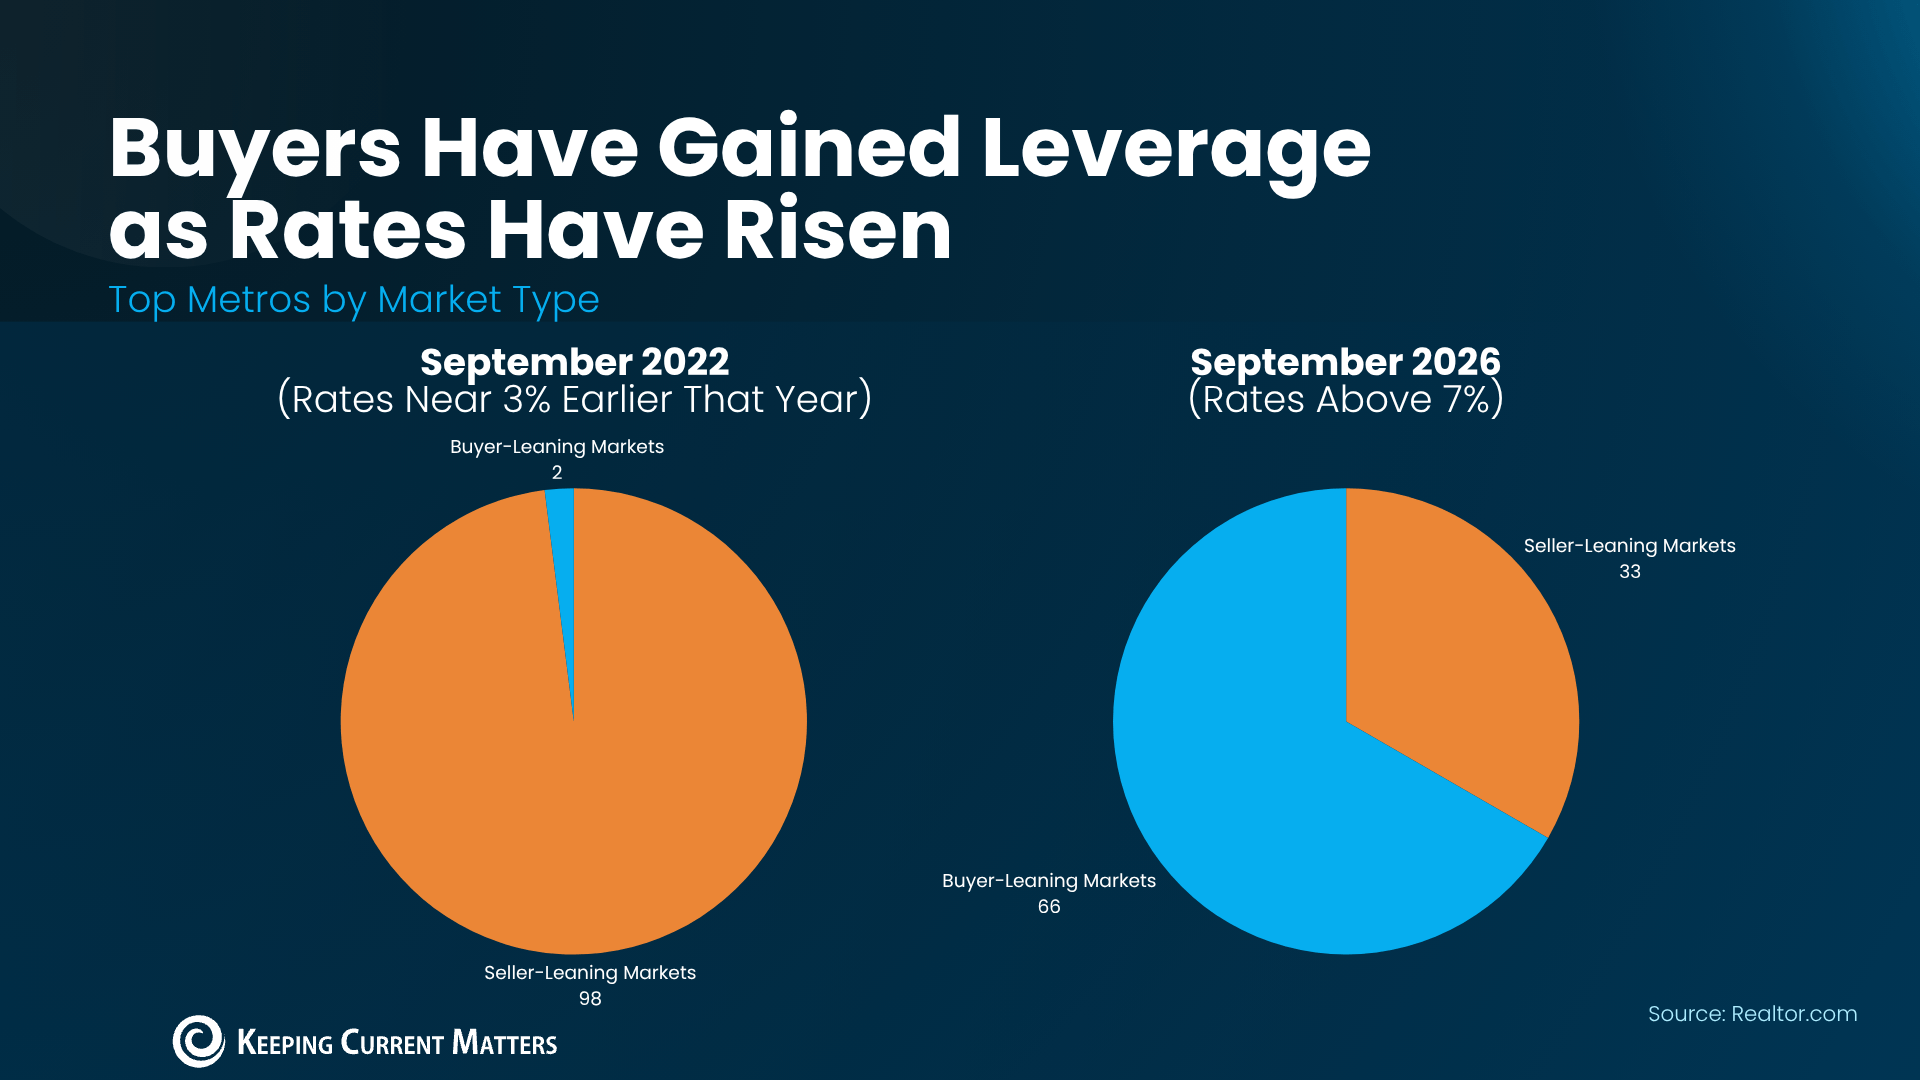
When rates began climbing in late 2022, buyer demand cooled, homes sat on the market longer, and inventory slowly rebuilt. That multi-year shift has officially tipped the scales. According to recent data from Realtor.com, roughly two-thirds (66) of the top 100 metro areas now lean in favor of buyers.
What Buyer Leverage Looks Like in Today’s Market
With more homes available for sale than we’ve seen in years, sellers can no longer just put a sign in the yard and wait for a bidding war. They have to compete for your offer. National Association of Realtors (NAR) Chief Economist Lawrence Yun sums up the shift:
“Higher inventory and lengthening days on market give buyers improved negotiating power.”
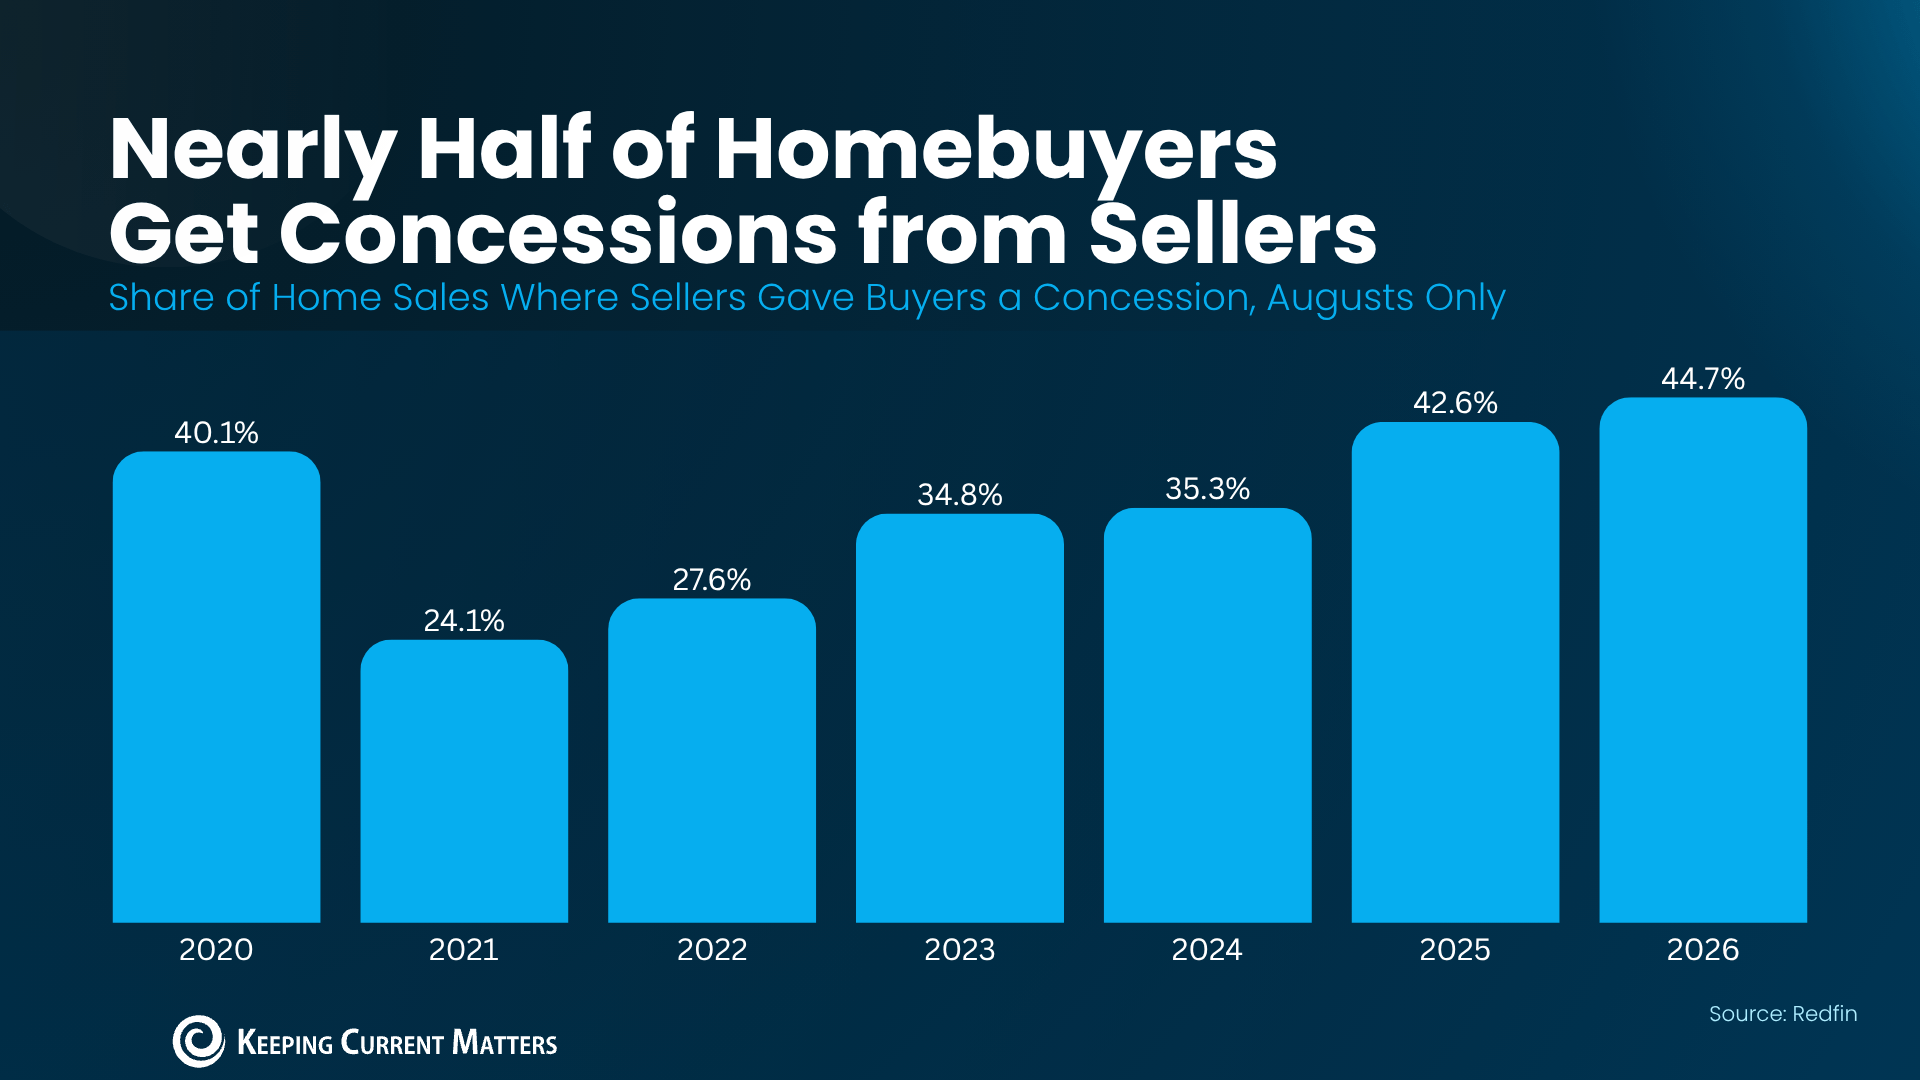
That leverage translates directly into real financial savings. Redfin reports that nearly half of all homebuyers are currently securing seller concessions. Instead of overpaying, buyers are successfully negotiating for:
Price reductions on homes that have been sitting on the market
Credits toward closing costs to keep more cash in your pocket upfront
Repair allowances after a thorough home inspection
Seller-paid rate buydowns, where the seller pays a lump sum at closing to temporarily or permanently lower your mortgage interest rate
Even if the headline mortgage rate isn't what you hoped for, a seller-funded rate buydown or a lower purchase price can bring your monthly payment right back into your comfort zone.
Why Waiting for Lower Rates Could Backfire
If you are still tempted to wait until rates drop, consider two major risks:
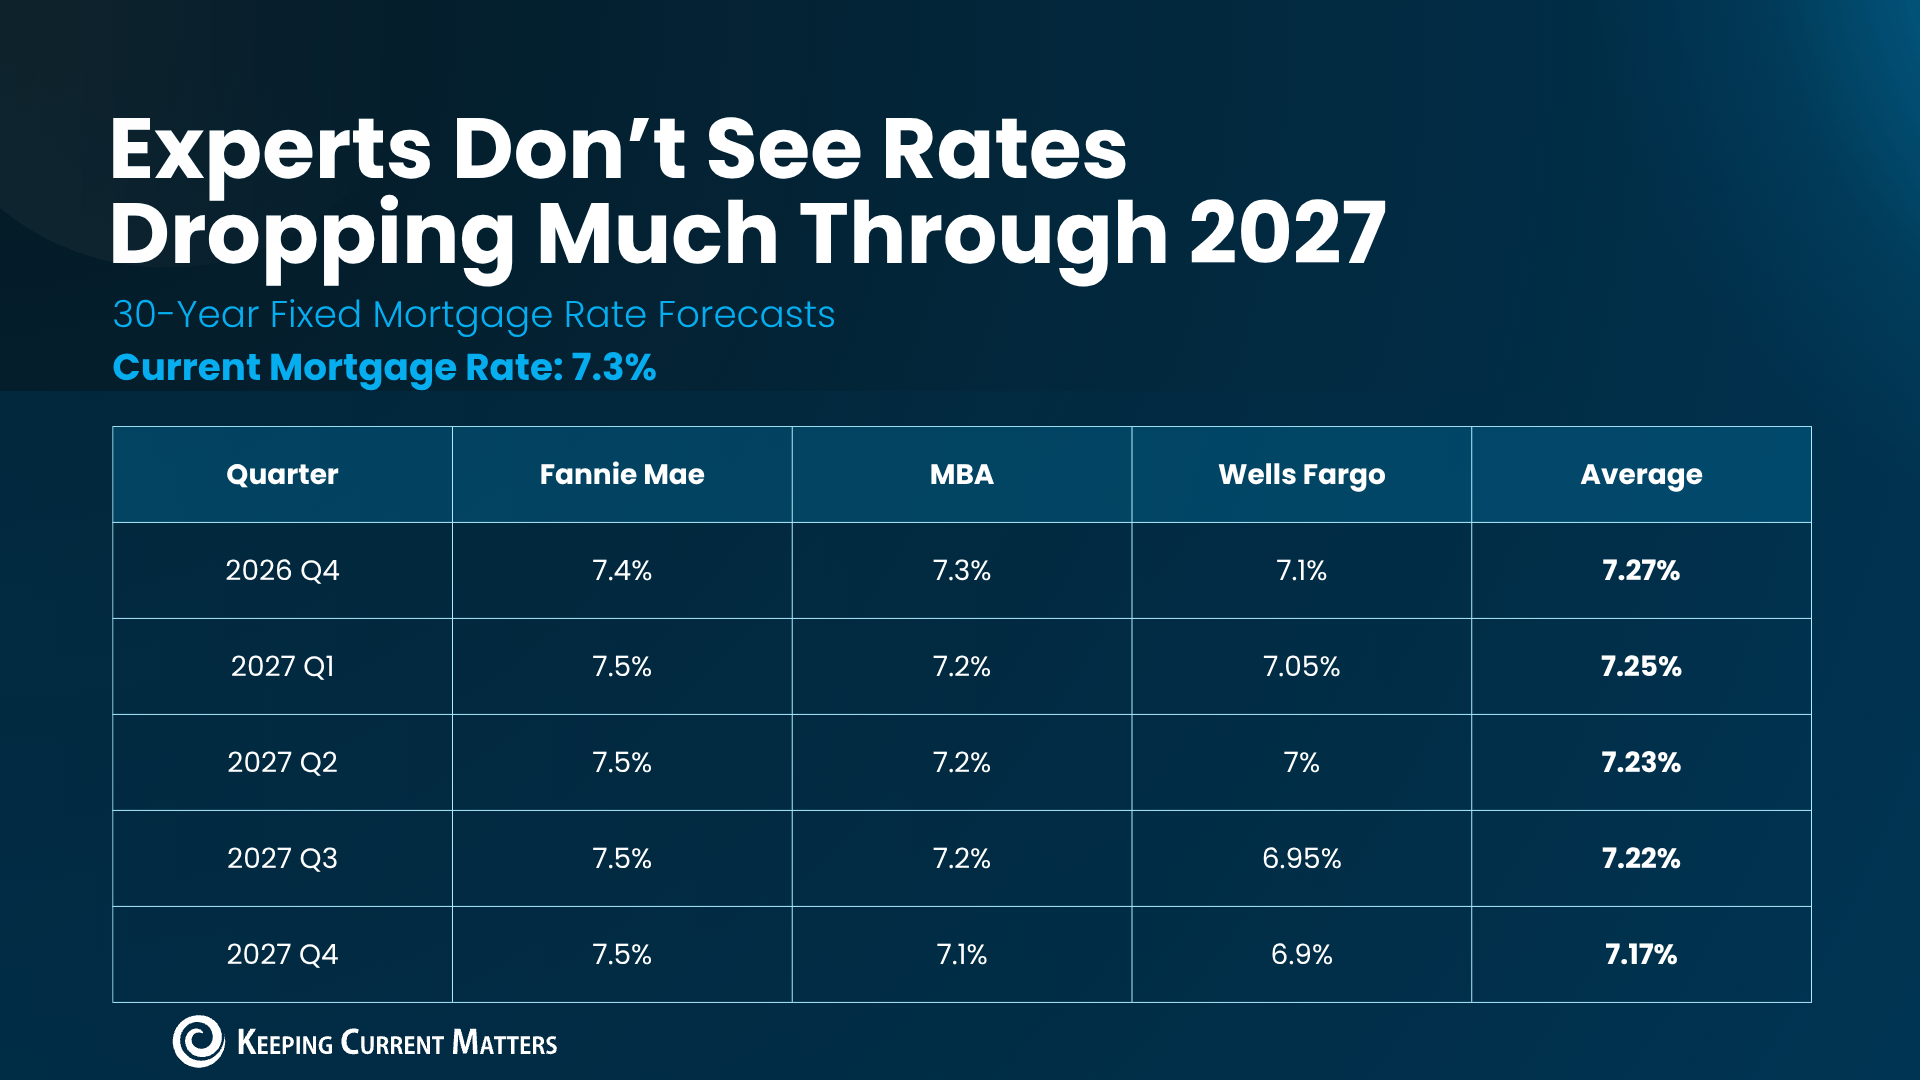
Rates aren't expected to plummet anytime soon. Major housing forecasters—including Fannie Mae, the Mortgage Bankers Association (MBA), and Wells Fargo—project mortgage rates to remain relatively steady without dramatic drops through 2027.
Lower rates will trigger a stampede. The moment rates meaningfully dip, millions of sidelined buyers will jump back into the market simultaneously. That sudden surge in competition will instantly wipe out price cuts, kill seller concessions, and hand all the leverage right back to sellers.
Waiting comes with a clear trade-off: you might eventually snag a slightly lower interest rate, but you will likely pay a higher home price and face fierce competition to get it.
Bottom Line
Buying a home is a personal financial decision, and you should never stretch beyond what makes sense for your budget. However, if you are ready to move, don't let today's rates scare you off before you see what sellers are willing to offer. Reach out to a local real estate agent to explore active listings in your area and find out how seller concessions or a rate buydown can make the numbers work for you today.
