Is Home Insurance Eating Up Your Budget? Here’s the Good News (and How to Save)
When you’re planning a move, every single dollar counts. That’s why watching home insurance costs climb year after year can feel so frustrating. In fact, data from Intercontinental Exchange reveals that insurance now accounts for 9.6% of the average monthly mortgage payment.
However, there is light at the end of the tunnel. The latest housing data shows that while costs are still rising, the pace of those increases is finally cooling down.
Here is what’s happening with insurance premiums right now—and what you can do to take control of your monthly bill.
1. Premium Hikes Are Slowing Down
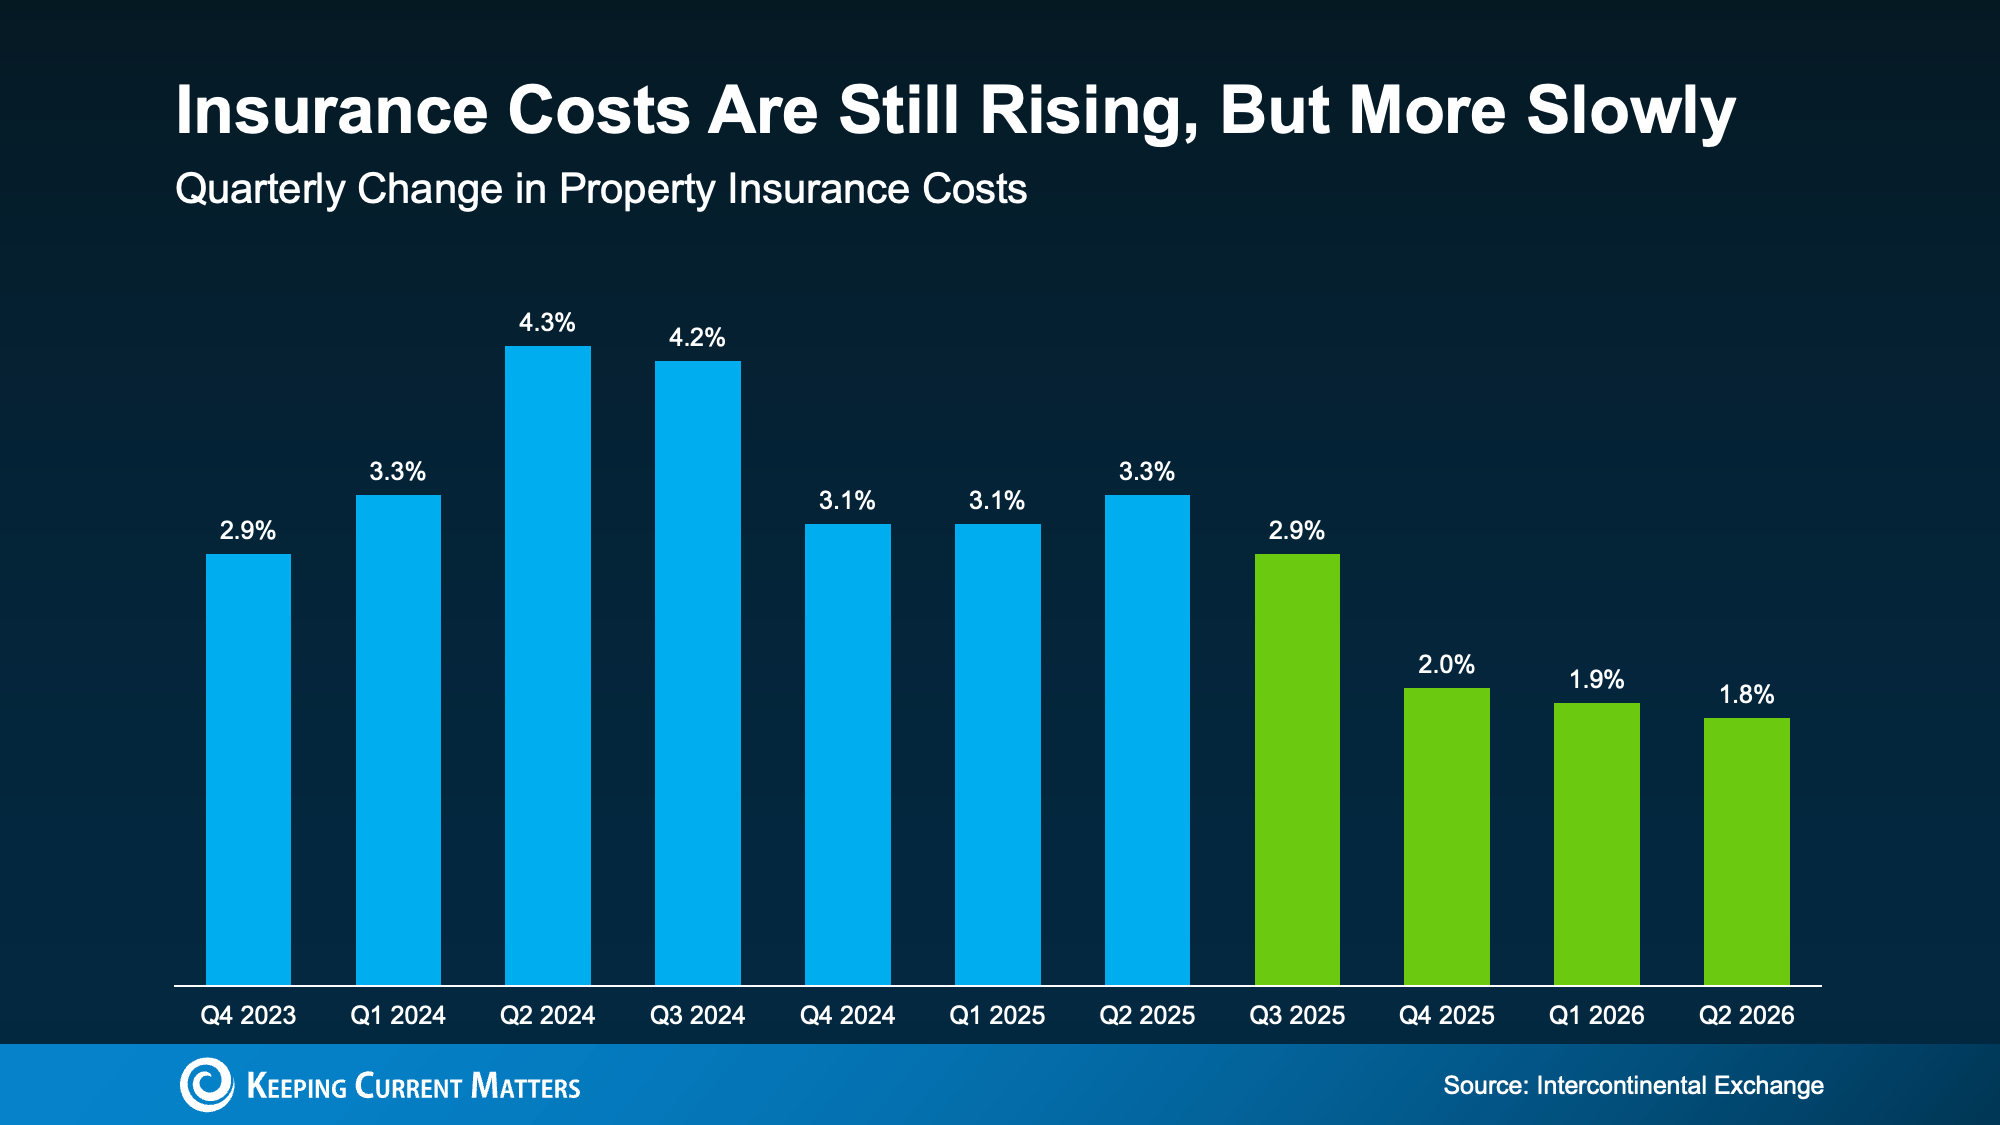
If it feels like insurance spiked dramatically over the last few years, you aren't imagining it. Back in mid-2024, home insurance premiums jumped by 4.3% in just a single quarter. Fast forward to the second quarter of this year, and that quarterly increase slowed to 1.8%—the lowest rate of growth in nearly three years.
As Andy Walden, Head of Mortgage and Housing Market Research at Intercontinental Exchange, notes:
"Property insurance has been a fast-growing component of the monthly mortgage payment, but this quarter’s data shows the pace of increase is finally slowing."
While premiums may still rise over time, they likely won't surge as aggressively as they did a couple of years ago.
2. Shopping Around Actually Pays Off
You don't have to simply accept higher rates. Shopping around for coverage can lead to substantial, real-world savings.
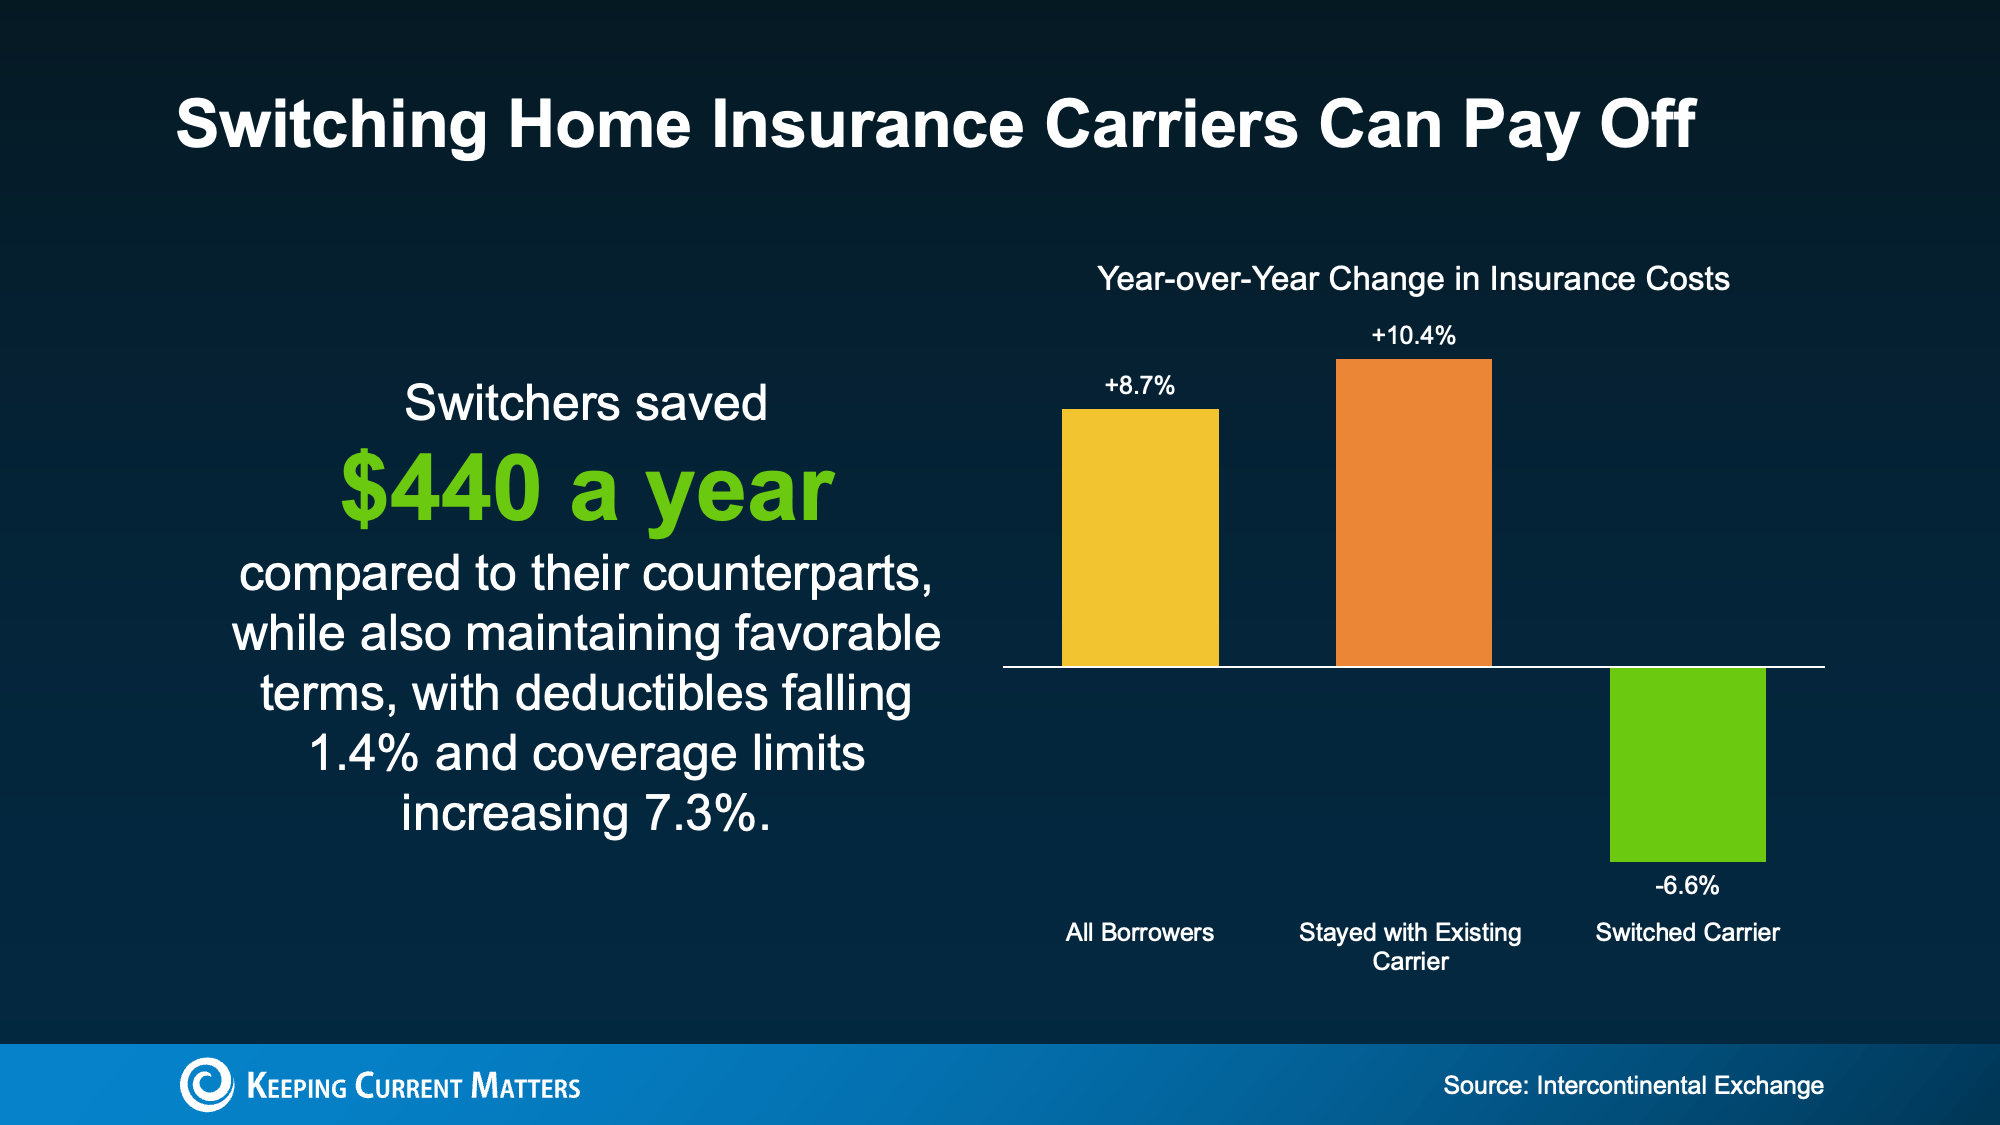
Intercontinental Exchange found that existing homeowners who switched insurance providers saved 6.6% on average. On the flip side, those who stayed with their current provider saw their rates jump by 10.4%.
That simple effort saved switchers an average of $440 per year—and they didn't have to sacrifice protection to get it. In fact, their deductibles dropped by 1.4% while their coverage limits actually increased by 7.3%.
For Current Homeowners: Don’t let your policy auto-renew without checking competing rates first.
For First-Time Buyers: Get quotes from multiple providers before choosing your policy.
3. Consider Buying New Construction
The structure you buy heavily influences what you'll pay each month. According to John Burns Research and Consulting (JBREC), brand-new homes are 10% to 15% cheaper to insure on average than older homes.
While a newly built home isn't the right choice for everyone, it’s a smart factor to consider if keeping your recurring monthly expenses low is a top priority.
The Bottom Line
Home insurance costs are certainly higher than they used to be, but you aren't powerless against rising rates. By shopping around before you buy, re-evaluating your policy every year, and working with trusted local real estate professionals, you can keep your monthly payments manageable.
