What Credit Score Do You Really Need to Buy a Home? (It’s Lower Than You Think)
Quick—what credit score do you need to qualify for a mortgage?
If a specific number jumped into your head, there’s a good chance it’s wrong. The reality is that credit score requirements are much more flexible than most people realize—and the way scores are measured is currently undergoing a major upgrade for the better.
Here is what you need to know about navigating today's changing credit climate.
1. Most People Overestimate What It Takes
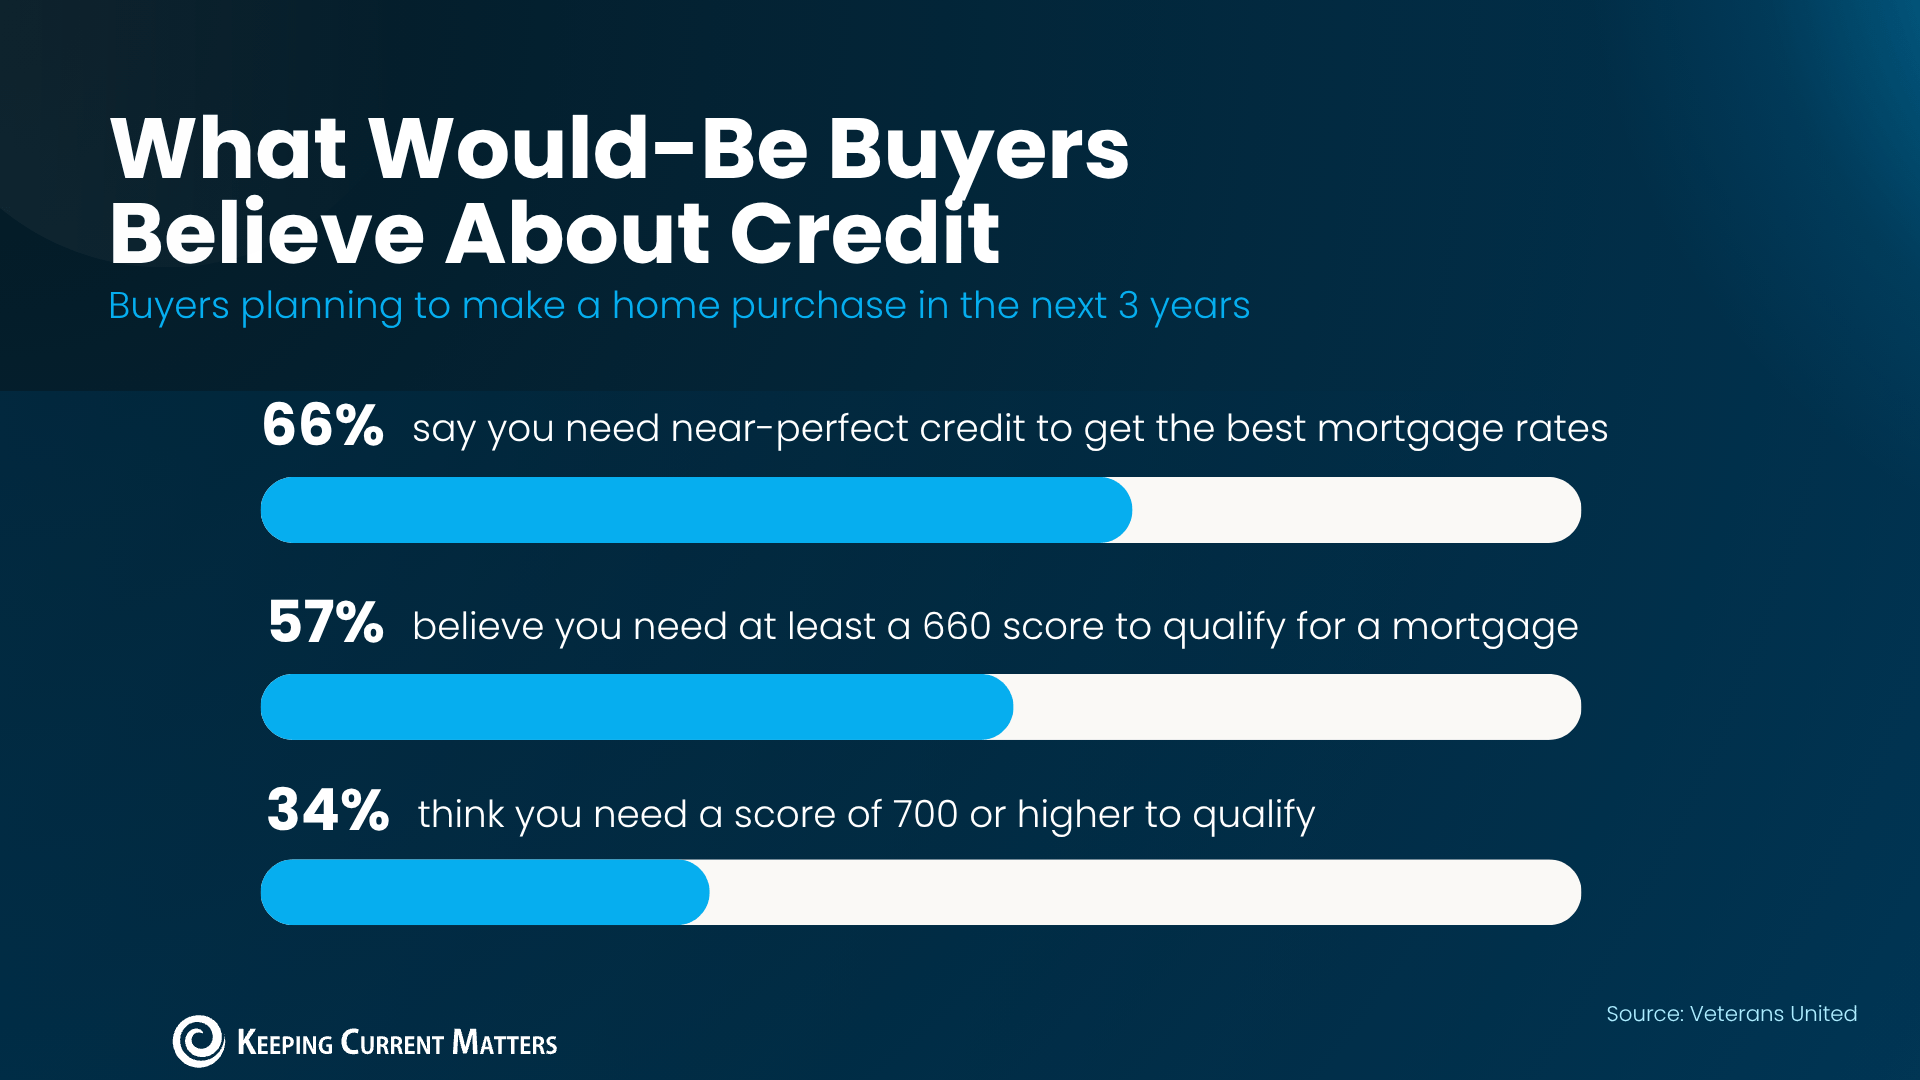
For nearly a decade, Fannie Mae has tracked what everyday consumers think it takes to qualify for a mortgage. The consistent finding? People overestimate the requirements. As recently as 2023, the average person guessed that a minimum credit score of 652 was required.
In reality:
The long-standing minimum benchmark for conventional loans backed by Fannie Mae and Freddie Mac is actually 620.
Government-backed options (like FHA loans) often accept scores even lower than that.
Even the 620 baseline isn't a hard-and-fast rule for every single scenario.
Why this matters: Guessing wrong holds people back. A renter who incorrectly assumes their credit score is "too low" might never take the first step to apply—missing out on homeownership unnecessarily.
2. Credit Scoring Rules Are Evolving
For decades, the mortgage industry relied almost exclusively on older credit scoring systems (known as Classic FICO). Today, that landscape is shifting toward a more modern, inclusive approach.
To help more Americans qualify for home loans, the Federal Housing Finance Agency (FHFA) approved updated credit scoring models, including FICO 10T and VantageScore 4.0.
More Inclusive Scoring: VantageScore estimates that its updated model can score roughly 33 million adults who were previously unscoreable under older Classic FICO models.
Score Variations: Because different models evaluate data slightly differently, the score you see on a free mobile app might differ from the score a mortgage lender pulls.
3. The Basics Still Apply (Focus on What You Can Control)
Even though scoring models are evolving, the habits that build a strong credit profile haven't changed. Following classic financial best practices will boost your score across all models—old and new alike:
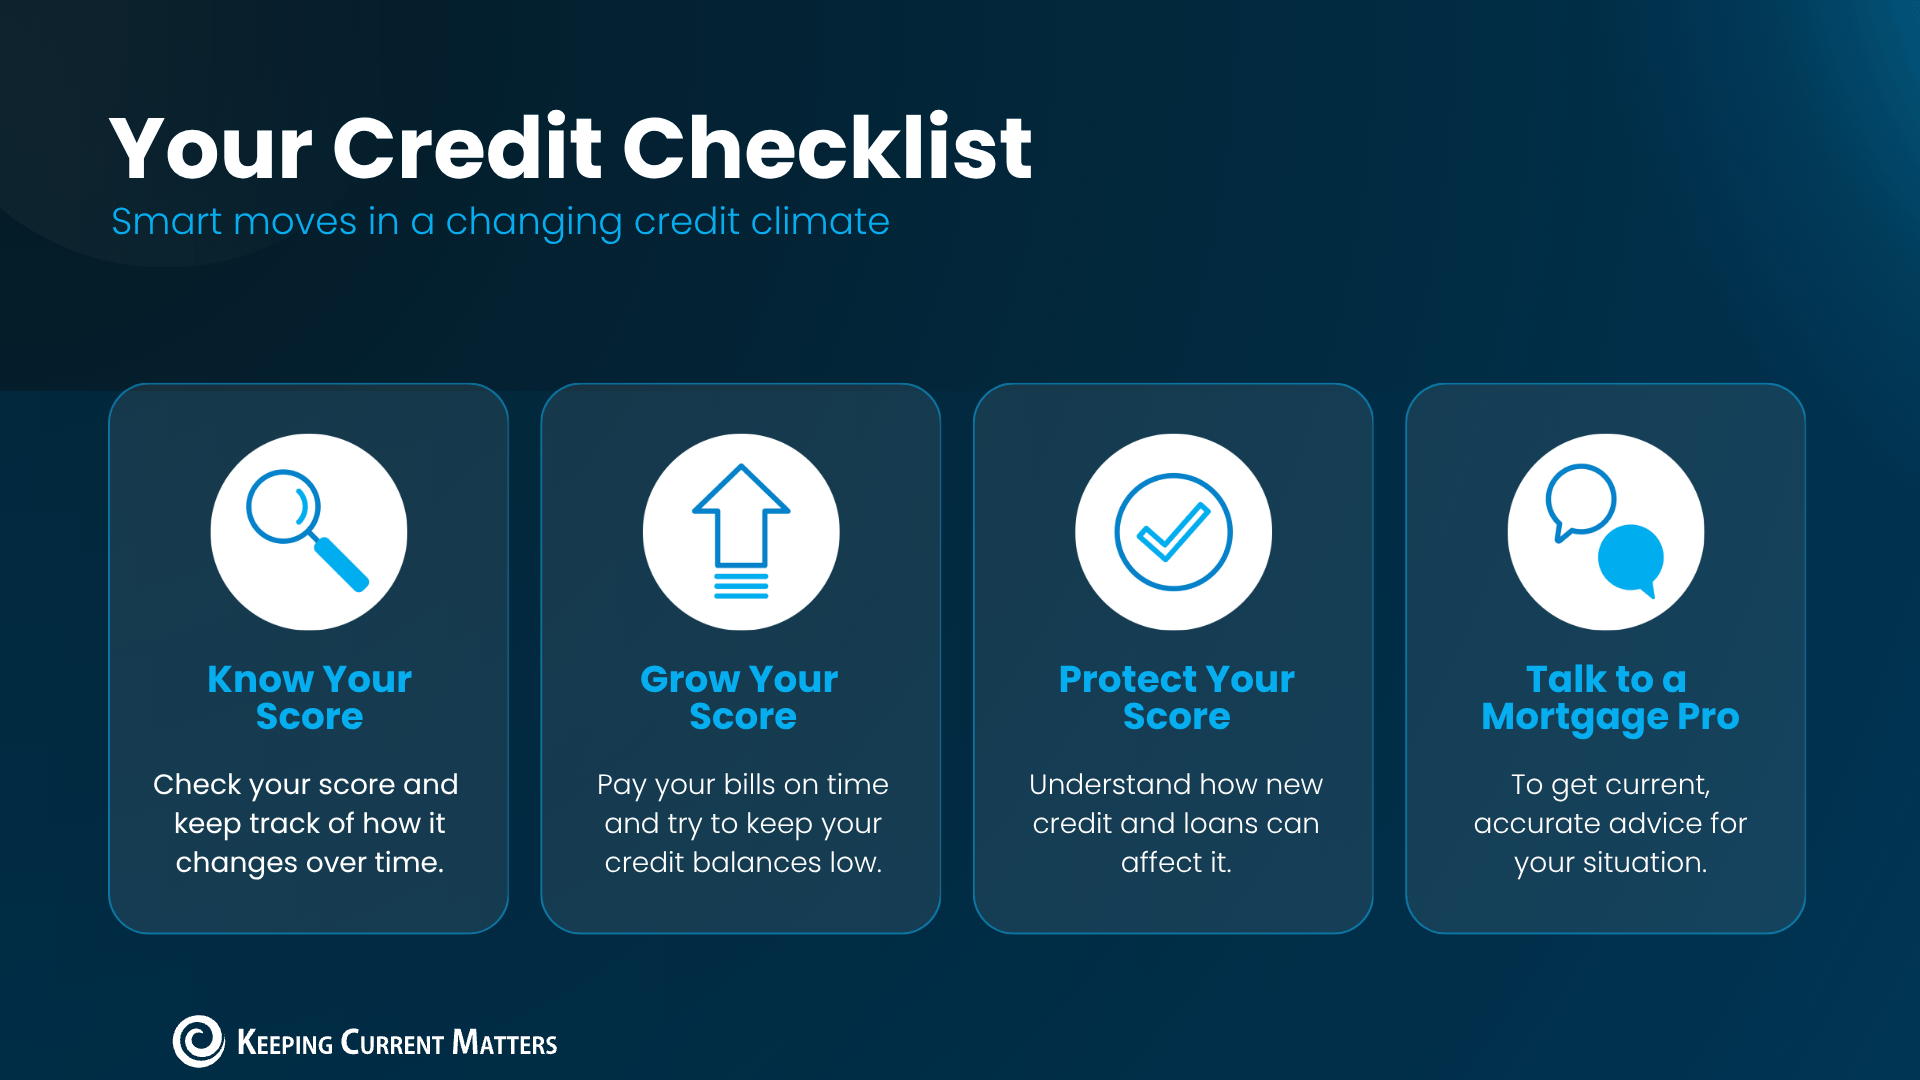
Pay every bill on time: Payment history remains the single largest factor in your score.
Keep credit card balances low: Aim to keep your credit utilization well below your total limit.
Avoid opening unnecessary lines of credit: Only apply for new credit when truly needed.
Monitor your credit report: Check regularly for errors, inaccuracies, or fraudulent activity.
Financial awareness, consistency, and a little discipline go a long way toward building a lender-ready profile.
The Bottom Line
Don't let outdated myths, internet charts, or mobile apps dictate your homebuying potential.
With credit rules shifting and misconceptions widespread, the best move you can make is to consult with a trusted loan officer early in the process. They can review your complete financial picture, offer tailored credit advice, and help you build a clear path to qualification.
You might be much closer to owning a home than you think!
